Good credit and steady income
Conventional
As little as 3% down for some buyers. Monthly mortgage insurance (PMI) can be removed once you reach 20% equity.
Run the numbers Get pre-approved
San Antonio mortgage broker
More lenders.
A mortgage built around you.
Applying takes 10–15 minutes online. I usually pull credit within 24 hours, unless you'd like me to wait.
Not ready yet? Book a free 15-minute call
Free · 15 minutes by phone · No credit pull
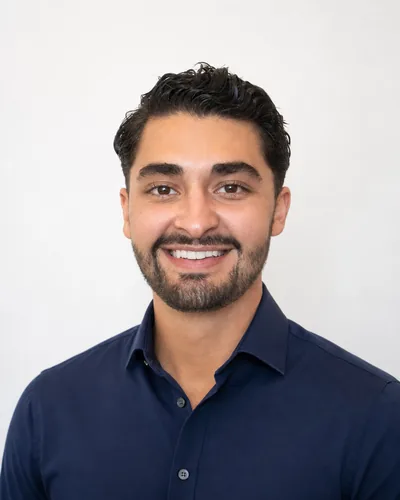 Talk with Austin(210) 294-4223
“He beat out all the other lenders and gave me a great deal and fast closing.”
“He took the time to answer any question I had and made things so easy and smooth for us!”
“Knowledgeable, patient, and stayed on top of everything from pre-approval to closing.”
“He anticipates potential issues and stays ahead of the details, making the entire process feel seamless.”
New to buying a home?
Pull your free credit reports at AnnualCreditReport.com and run a rough payment estimate so you know your comfortable range.
I review your income, savings and credit, compare lenders, and give you a pre-approval letter with a price range to shop in.
Your real estate agent finds homes, writes offers and negotiates. Your pre-approval letter shows sellers you're ready.
In Texas you'll usually pay earnest money and a small option fee, then use the option period for a home inspection.
The lender checks the home's value and verifies your paperwork. Answering document requests quickly keeps your closing date on track.
You'll get your Closing Disclosure at least 3 business days before closing. Then you sign at the title company and the home is yours.
Not sure which step you're on? That's what the call is for.
Book a free 15-minute callPersonal from the first hello
I come from three generations of San Antonio real estate. My grandmother spent more than 10 years in luxury real estate, and my dad has spent more than 30 and still does. I almost became a realtor too, then found lending and never looked back.
Since 2020 I've helped hundreds of families. As a broker at Harbor Financial Mortgage, I shop lenders for you and stay with you through closing. My favorite part is still the first call: answering your questions and building your game plan.
Calls and texts 7 days a week, evenings included. I get back to you the same day, usually within a couple of hours.
Read my story austin@hf-mortgage.comLoan options in plain English
You don't need to know the names. Find the line that sounds like you, and I'll confirm the best fit after comparing lenders.
Good credit and steady income
As little as 3% down for some buyers. Monthly mortgage insurance (PMI) can be removed once you reach 20% equity.
Run the numbersRebuilding credit or a smaller down payment
3.5% down with a credit score of 580 or higher. More flexible on credit history.
Read the FHA guideVeterans, service members and eligible spouses
No down payment and no monthly mortgage insurance for eligible buyers.
Read the VA guideHomes in eligible areas outside the city core
No down payment for eligible buyers, with household income limits.
Ask me about itSelf-employed buyers
Qualify using your business or personal bank deposits instead of tax returns.
Read a client storyBuying a rental property
Qualify mostly on the rent the property can bring in, rather than only your personal income.
Ask me about itBuilding a home
Financing for building on your lot or with a builder, then turning it into your long-term mortgage.
Ask me about itDoctors and some medical professionals
Low down payment options that treat student loans and new contracts differently.
Ask me about itCalculator links open my free calculator site, HomeBuyingCalc.com. Loan availability and eligibility vary by borrower, property, and program.
You don’t need to have it all figured out to get in touch.
Applying takes 10–15 minutes online. I usually pull credit within 24 hours, unless you'd like me to wait.